What a Home Warranty Covers Versus Homeowners Insurance
Homeowners insurance pays when something sudden damages your home, like a fire, a windstorm, or a break-in. A home warranty pays to repair or replace appliances and home systems that fail from ordinary wear and tear, which insurance deliberately excludes.
That’s the short version of home warranty vs homeowners insurance. They sound similar, they’re often sold around the same time you buy a house, and people regularly assume one replaces the other. It doesn’t.
Home warranty vs homeowners insurance, side by side
| Homeowners insurance | Home warranty | |
|---|---|---|
| What it covers | The structure, your belongings, and liability if someone is hurt on your property | Repair or replacement of listed systems and appliances, such as HVAC, water heaters, and dishwashers |
| What triggers it | A covered peril: fire, wind, hail, theft, certain water damage | A covered item breaking down from normal use |
| How you pay | Annual premium plus a deductible per claim | Annual or monthly fee plus a service-call fee per visit |
| Required? | Almost always, if you have a mortgage | Never required |
| Who regulates it | State insurance departments | Varies by state; often treated as a service contract |
A simple example: if a kitchen fire ruins your oven, that’s an insurance claim. If the oven’s heating element just dies one Tuesday, insurance won’t touch it, and that’s the kind of failure a warranty is built for.
Where each one quietly stops paying
Insurance policies exclude maintenance problems and gradual damage. A slow leak that rotted the subfloor over months is usually denied, and flood and earthquake damage generally need separate policies. Read the exclusions page before you need it, not after.
Home warranties have their own fine print, and it’s where most disappointment comes from. Watch for:
- Per-item payout caps that may not cover a full replacement of an expensive system
- Exclusions for pre-existing conditions or items that weren’t “properly maintained”
- The provider choosing the contractor, not you
- Waiting periods before coverage starts
So which situations favor a warranty? It tends to make the most sense when your furnace, water heater, and major appliances are older but still running, and a surprise repair bill would be hard to absorb. It makes less sense in a newer home where many items are still under the manufacturer’s warranty, or if you already keep an emergency fund big enough to cover a repair. Some homeowners skip the contract and put the same monthly amount into a savings account instead.
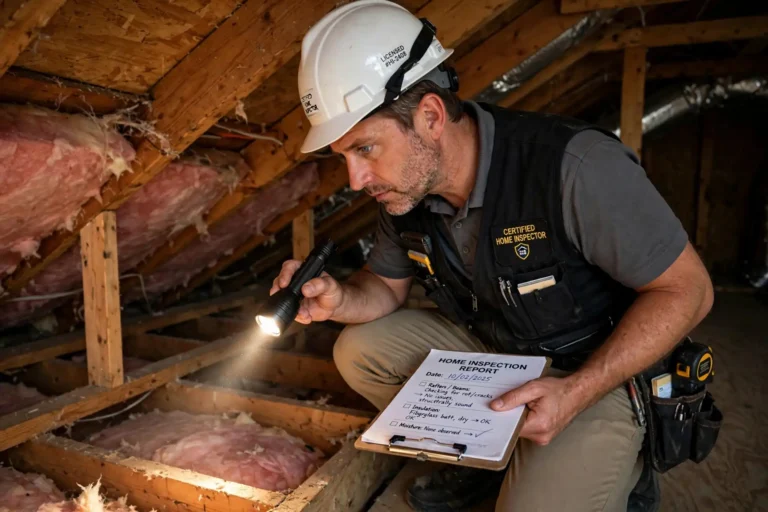
If you’re buying, the seller sometimes includes a warranty for the first year. It’s worth having, but it doesn’t replace a proper look at the house. A good home inspection before you buy tells you which systems are near the end of their life, which helps you judge whether a warranty is worth paying for once the free year runs out.
For plain explanations of policy types and common exclusions, the Insurance Information Institute is a solid, non-sales starting point.
Keep the insurance no matter what. Treat the warranty as optional, and only buy it after you’ve read the coverage caps and compared them with what a repair would cost you out of pocket.