How Travel Insurance Actually Works, in Plain Terms
Travel insurance pays out for a narrow, specific list of things that go wrong on a trip — not everything that goes wrong. Read the policy before you buy, because the coverage that sounds most reassuring in the marketing, like “trip cancellation,” is usually the one with the most exceptions attached to it.
What Most Policies Cover
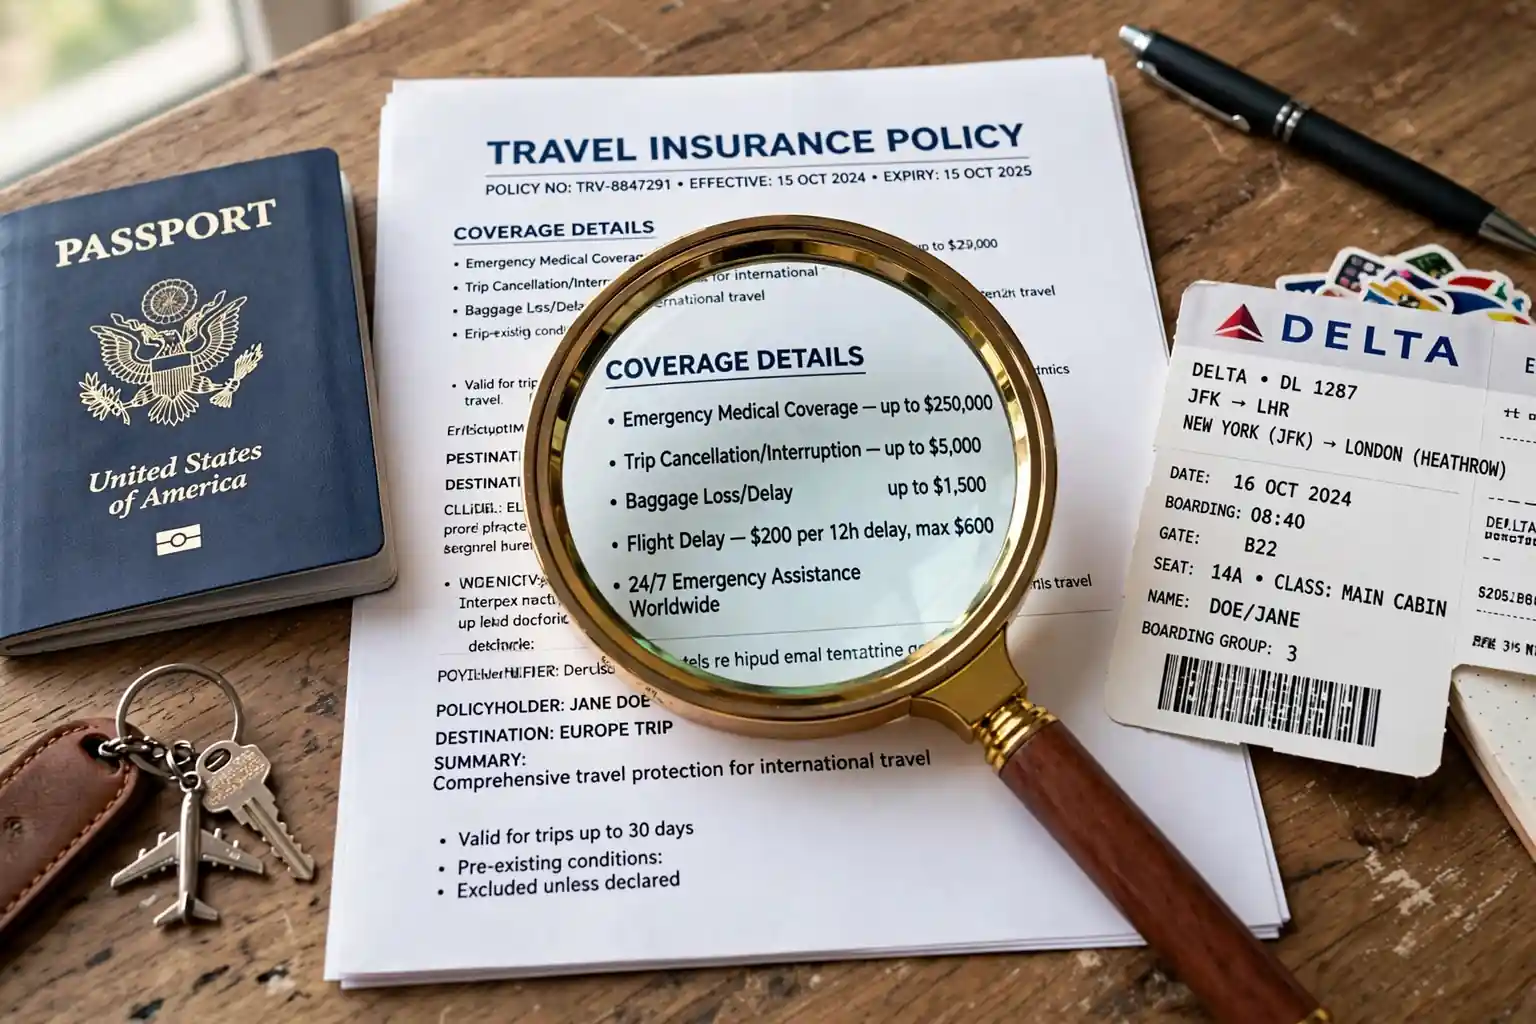
A standard travel insurance policy bundles a few kinds of protection: trip cancellation or interruption reimbursement if you get sick, a family member dies, or your flight is canceled for a covered reason; emergency medical care and evacuation if you’re hurt or ill abroad, which matters most in countries where your regular health plan doesn’t apply; and baggage protection if a bag is lost, delayed, or stolen. Emergency medical evacuation is often the piece worth paying for on its own — a medical flight home from overseas can run into six figures, and few domestic health plans touch that cost.
Where Coverage Runs Out
Most exclusions surprise people at the worst possible moment. Common gaps:
- Pre-existing medical conditions, unless you bought a “cancel for any reason” upgrade or a policy with a specific waiver, purchased within a set window after your first trip deposit.
- Government travel advisories — a country being added to a warning list rarely triggers cancellation coverage on its own.
- Extreme sports like off-piste skiing, deep scuba diving, or motorcycling, which often need a separate rider.
- Change of mind — deciding you don’t want to go isn’t a covered reason; only specific, named events are.
Vague reasons like feeling nervous about a trip almost never qualify. The policy lists the covered reasons explicitly, and if your situation isn’t on that list, the claim gets denied regardless of how reasonable it feels.
How to Compare Plans
Skip the marketing copy and go to the coverage limits and exclusions page — usually a document called the “certificate of insurance” or “policy wording.” Check three numbers: the medical evacuation limit (aim for at least $100,000), whether medical coverage is primary or secondary (primary pays first, without you fighting your regular insurer afterward), and the cancellation reimbursement percentage (100% is standard; “cancel for any reason” upgrades usually cap at 50–75%). The U.S. Travel Insurance Association publishes consumer guidance that’s a useful starting point if the policy language gets confusing.
If you’re weighing whether a trip needs coverage at all, building it into your pre-trip checklist rather than an afterthought means you catch the pre-existing-condition waiver window before it closes. And if your itinerary already involves nonrefundable connections, the same booking mistakes that cost you money are often the exact scenarios a cancellation policy is meant to cover.
A policy is only as good as the claim you never have to argue about — buy for the risk that would genuinely hurt, not the one that sounds most complete on the sales page.
Travel insurance is one of those products everyone nods along about and almost nobody truly understands until they need it. The overview above explains the basics in plain language. What follows is the next layer: how policies are actually structured, how claims really move from incident to payout, and where the fine print tends to bite.
A Travel Insurance Policy Is a Contract, Not a Safety Net
The most useful mental shift is to stop thinking of travel insurance as a general promise and start thinking of it as a contract that pays for specifically listed events. Every policy has a declarations page naming what is covered, a list of exclusions naming what is not, and definitions that decide what words like “injury” and “trip” actually mean. Two similar policies can define those words differently enough to change a claim’s outcome.
This is why reading the actual policy document matters more than reading the marketing summary. The summary tells you what the insurer wants you to know. The certificate of coverage tells you what they are obligated to do. The relevant sections are usually short: the covered reasons for cancellation, the medical coverage terms, and the exclusions.
One more structural point: most travel insurance is sold as a package combining several coverage types in one policy, but the components have separate limits. A policy advertising $50,000 of coverage might mean $50,000 for trip cancellation, $25,000 for medical, and $1,000 for baggage. Always check which number applies to the scenario you actually worry about.
The Four Types of Coverage Most Policies Bundle
Trip cancellation and interruption
This is the core of most policies. It reimburses prepaid, nonrefundable trip costs if you must cancel or cut short a trip for a covered reason: typically serious illness or injury, a death in the family, jury duty, or a natural disaster at the destination. Canceling because you changed your mind or found a cheaper flight is not covered under standard terms. That gap is exactly what the “cancel for any reason” upgrade exists to fill, usually reimbursing 50 to 75 percent of costs.
Emergency medical and evacuation
This covers medical treatment for illness or injury during the trip, plus emergency evacuation to adequate care if local facilities cannot handle the problem. Evacuation from a remote area or a foreign hospital can cost tens of thousands of dollars, which is why this coverage matters most on adventure trips and in countries where your domestic health plan does not follow you. Check whether your regular health insurance covers you abroad before deciding how much of this you need.
Baggage loss, delay, and damage
Baggage coverage reimburses the depreciated value of lost or stolen belongings and covers essentials if your bags are delayed, usually after a waiting period of six to twelve hours. The limits are modest on most policies, often $1,000 to $2,500 total with per-item caps. If you travel with expensive gear, check the per-item limit specifically.
Travel delay and missed connections
Delay coverage kicks in after a set number of hours and pays for meals, hotels, and rebooking costs. Missed-connection coverage helps when a delay on one leg causes you to miss the next. The hourly thresholds and daily caps vary widely, so compare these numbers directly if you book tight itineraries.
How a Claim Actually Moves From Incident to Payout
Understanding the claims process before you travel changes how you behave during a crisis, which is precisely when clear thinking is hardest. The process has three phases, and most denied claims fail at phase one.
Document at the moment, not later
Claims live or die on documentation created at the time of the event. Get the airline’s written confirmation of a cancellation or delay. Keep every receipt for expenses you want reimbursed. If you see a doctor abroad, get itemized bills and a written diagnosis. Take photos of damaged baggage and delayed baggage tags.
File promptly and completely
Most policies require you to notify the insurer quickly, sometimes within 24 to 72 hours for medical emergencies, and to file the formal claim within a set window, often 90 days. File online if the option exists, attach everything at once, and keep copies of the entire submission. An adjuster cannot approve what it cannot see.
What adjusters actually look for
The adjuster checks three things: did a covered event occur, does the documentation prove it, and do the claimed expenses fall within the policy limits. Straightforward claims with complete documentation are often paid in a few weeks. If a claim is denied, the denial letter must explain why, and most policies include an appeals process. Before buying, you can check that the company selling the policy is legitimate and licensed through consumer resources from the National Association of Insurance Commissioners.
The Exclusions That Surprise People
Pre-existing medical conditions are the biggest exclusion. Standard policies typically exclude them, though many insurers waive the exclusion if you buy the policy within a short window after your initial trip deposit, often 14 to 21 days. If anyone traveling has a health condition, that purchase window matters enormously.
High-risk activities are another common gap. Scuba diving, mountaineering, backcountry skiing, and similar pursuits are frequently excluded or require a sports rider. Alcohol-related incidents are excluded almost universally. So are losses from civil unrest or war, and travel against official government advisories. Some policies also require you to comply with destination entry rules, which is one more reason that finding official visa information from government sources before you book is worth the effort.
No policy covers everything, and the exclusions are not hidden. They are printed in the certificate. Terms vary by policy and by state, so treat any general advice, including this article, as a starting point for reading your own documents, not a substitute for it.
When to Buy and How Much Coverage Is Enough
How to File a Travel Insurance Claim Without the Headache
The claim is where travel insurance either pays off or falls apart, and the difference is almost always documentation. Collect it in real time, not after you get home.
Start a claim folder on your phone the moment something goes wrong. Photograph everything: the cancelled-flight notice, the hotel receipt, the pharmacy bill, the broken suitcase. Get the police report number if theft is involved — most insurers require a report filed within 24 hours for theft claims, and without it your claim is dead on arrival. Save every email the airline sends you about delays or cancellations.
File fast. Most policies require you to notify the insurer within 30 to 90 days, but filing within the first week is smarter: your receipts are fresh and your memory is reliable. Most insurers now accept claims through an app or web portal, and a complete filing with photos usually takes under an hour.
The three most common denial reasons are all avoidable. First, pre-existing conditions — if the policy excludes them, it excludes them; no amount of arguing changes it. Second, missing receipts — insurers cannot reimburse what you cannot prove, so keep every receipt over $10. Third, late filing — the deadline is in the policy’s fine print and it is strictly enforced.
If a claim is denied, appeal once with any documentation you missed. Appeals with new evidence succeed far more often than people expect.
Buying soon after your first trip deposit unlocks the pre-existing condition waiver on many policies and starts your cancellation coverage earlier. Waiting until the week of departure still gets you medical and baggage coverage, but you lose the early-purchase benefits.
As for amounts, match coverage to the trip, not to your anxiety. A $1,500 domestic weekend needs far less cancellation coverage than a $12,000 honeymoon booked a year out. Medical coverage deserves more weight on international trips, especially outside countries with reciprocal healthcare arrangements. And check what you already have before buying: premium credit cards often include trip cancellation, delay, and baggage coverage. Paying for a standalone policy that duplicates your card’s benefits is one of the quietest wastes of money in travel.
Slot the insurance decision into the week before an international trip at the latest, alongside document checks and confirmations, so it gets a calm decision instead of a rushed one.
Frequently Asked Questions
Is travel insurance worth it for cheap domestic trips?
Often not as a standalone purchase. The financial risk on a low-cost domestic trip is small, and your health insurance already covers you at home. The exception is a trip with significant nonrefundable costs or a traveler with health concerns.
Does travel insurance cover me if I get sick with something common, like the flu?
Yes, if the illness forces you to cancel before departure or need treatment during the trip, and a doctor confirms it. What is not covered is canceling out of general worry about getting sick. The distinction is always between a documented medical event and a change of mind.
What is the difference between primary and secondary medical coverage?
Primary coverage pays first, without involving your regular health insurance. Secondary coverage pays only what your health plan does not. Primary costs more but simplifies claims enormously, especially abroad where your domestic insurer may be slow to respond or cover nothing at all.
Can I buy travel insurance after something goes wrong?
No. Insurance covers unforeseen events, and anything already known or already happening, from a forecasted hurricane to an illness diagnosed before purchase, is excluded. This is why buying early matters: the coverage has to be in place before the risk materializes.
Do I need travel insurance if my credit card offers it?
Maybe not a full standalone policy, but read the card’s benefit guide carefully. Card coverage often has lower limits, excludes pre-existing conditions entirely, and may require you to have paid for the trip with that card.
Conclusion
Travel insurance is simpler than it looks once you see the structure: a contract covering listed events, bundled into a few coverage types, with exclusions you can actually read and a claims process that rewards documentation. Buy early, match the coverage to the trip, read the certificate, and keep your receipts. Do that, and the policy becomes what it should be, a quiet backstop you rarely think about. For more plain-language travel guides, from trip planning to on-the-road know-how, visit Factblaze.