What Travel Rewards Credit Cards Offer Beyond Points
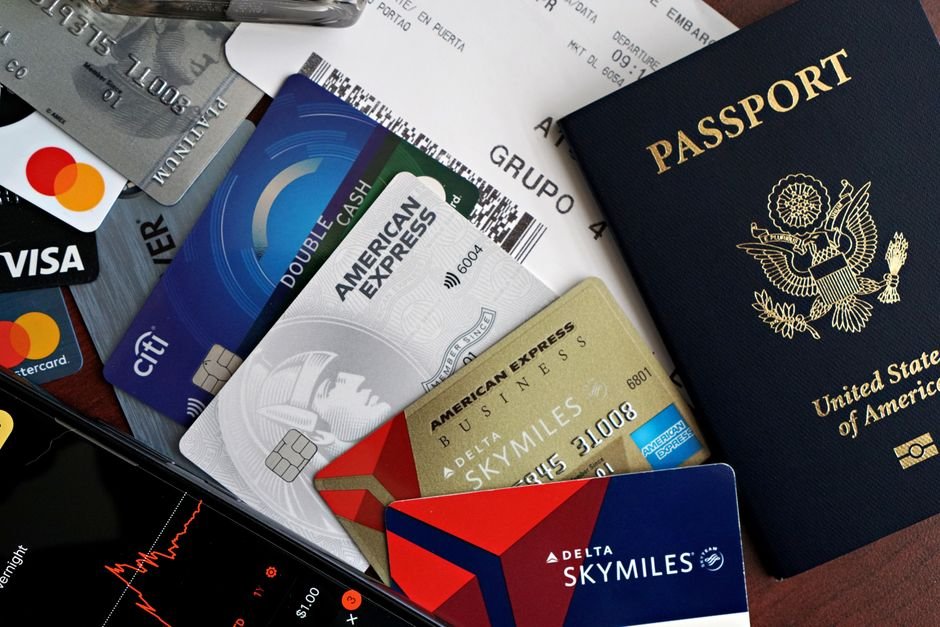
Beyond points and miles, travel rewards credit card benefits often include trip insurance, rental car coverage, lounge access, and fee credits you may never use. These perks can be worth more than the rewards themselves, but only if you know they exist and meet their conditions.
The catch is that every card and issuer handles them differently. What follows is a map of the common categories, not a promise about any particular card, so treat your card’s own benefits guide as the final word.
Travel rewards credit card benefits people forget to use
Trip cancellation and interruption coverage is the perk people most often forget. Some cards reimburse prepaid, nonrefundable costs if a covered reason, such as illness or severe weather, stops or cuts short a trip. The usual condition is that you paid for the trip, or part of it, with that card. Coverage limits, covered reasons, and who counts as a traveler vary widely, so read the terms before relying on it instead of a standalone policy. If you’re comparing the two, it helps to understand how travel insurance works in general first.
Rental car collision coverage is another. Many cards offer damage coverage when you decline the rental company’s collision waiver and pay with the card. The key word to look for is whether it’s primary or secondary. Primary coverage pays first; secondary coverage only kicks in after your own auto insurance, which can mean a claim on your personal policy. Coverage also tends to exclude certain countries, vehicle types, and long rentals.
Then there are smaller protections that quietly save money: reimbursement for essentials when a bag is delayed, coverage for lost luggage, and trip delay benefits that pay for a meal or hotel room after a long delay. These usually have waiting periods and dollar caps, and they almost always require receipts.
Lounge access sits at the premium end. Some cards include a lounge network membership or access to the issuer’s own lounges. Check whether guests are included, how many visits you get, and whether access depends on the airline you’re flying that day.
Fee credits are easy to leave on the table. Some cards reimburse the application fee for trusted traveler programs, offer annual travel credits, or cover checked bag fees on a specific airline. Many of these must be activated or enrolled in first, and they reset on a schedule.
A card with no foreign transaction fees matters more than it sounds. On a card that charges one, every purchase abroad costs a few percent extra, which quietly erodes whatever you’re earning. That pairs with the advice on mistakes people make exchanging currency abroad, since card fees and exchange markups stack.
What the perks cost you
None of this is free. Cards with rich travel benefits often carry annual fees, and carrying a balance at high interest wipes out the value of any perk. The Federal Trade Commission’s consumer credit pages explain card costs and your rights in plain language.
Before your next trip, find your card’s benefits guide, usually on the issuer’s website, and note what’s covered, what needs activating, and what proof a claim requires. A perk you don’t know about is worth exactly nothing.